57th GST Council addresses concerns across registration, returns, refunds, input tax credit
The 57th GST Council meeting’s recommendations address concerns across registration, returns, refunds, input tax credit and dispute resolution, seeking to strengthen trade, clarify tax treatment and widen opportunities for small sellers and service exporters, according to a government factsheet on Saturday.

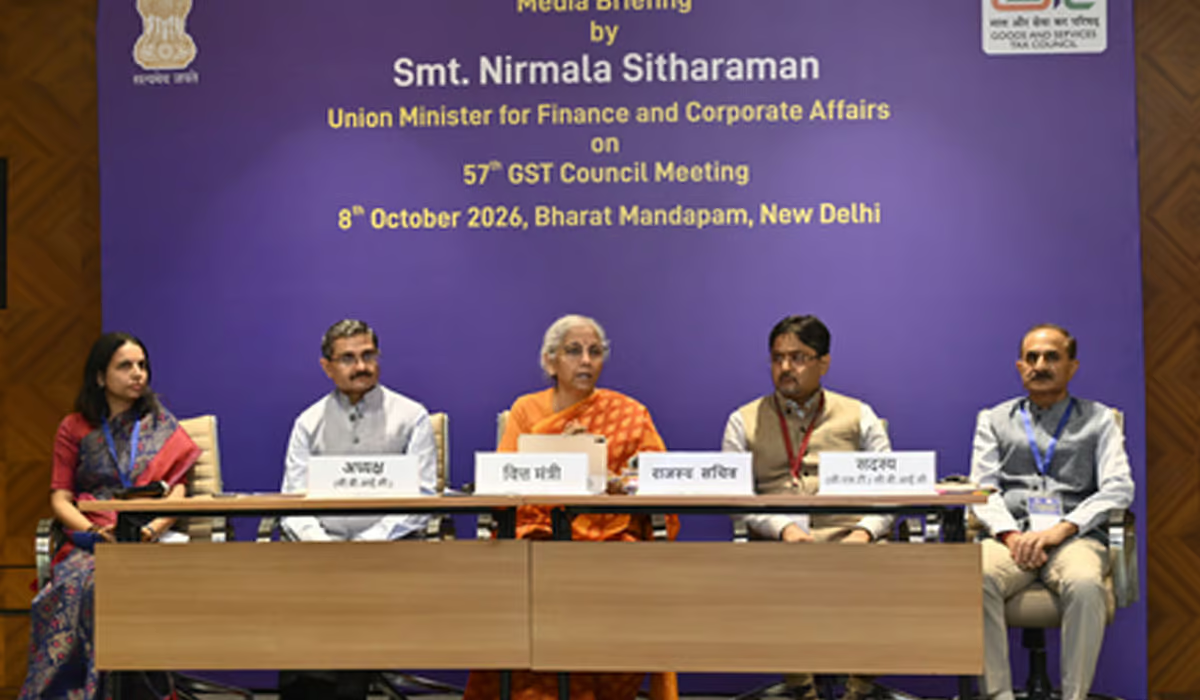
New Delhi: The 57th GST Council meeting’s recommendations address concerns across registration, returns, refunds, input tax credit and dispute resolution, seeking to strengthen trade, clarify tax treatment and widen opportunities for small sellers and service exporters, according to a government factsheet on Saturday.
The GST 2.0 reforms come as registered taxpayers increased from around 60 lakh in 2017 to 1.70 crore (till September 2026).
As on September 30, the GST System had cumulatively processed 3,053 crore invoice uploads and 833.82 crore e-way bills. Gross GST collections reached Rs 12.46 lakh crore during April-September 2026, registering an increase of 11.6 per cent year-on-year.
Now, for an easy and near real-time updation, the Council suggests automatic acceptance of amendments to registration particulars. This would be enabled on the portal, except for changes relating to the Principal Place of Business (PPoB). For taxpayers registered through the automatic route, amendments to all registration particulars, including PPoB, would be accepted automatically, according to the factsheet.
“The cancellation applications will be accepted automatically after pending returns are filed and all dues are paid. This would apply to taxpayers who have not passed on ITC exceeding Rs 2.5 lakh in any month. It would also apply where ITC exceeded Rs 2.5 lakh in a month, if the final return is filed within the specified time,” according to the statement.
The reforms suggested by the GST Council provide a simplified registration mechanism for small taxpayers making supply through E-commerce platforms.
Moreover, refunds of excess cash ledger balances would become automatic, facilitating faster availability of funds for businesses. The acknowledgement period would be reduced from 15 to 10 days. Deemed acknowledgement will apply where no response is issued.
Based on risk assessment, 90 per cent of claimed amount is expected to be sanctioned, for refund claims on account of zero-rated supplies and inverted duty structure, said the statement.
No show-cause notices will be issued if the tax amount involved is less than Rs 10,000. Pending notices on the date of the provision and appeals involving amounts below Rs 10,000, will be decided based on the Rs 10,000 minimum threshold, as if it were applicable when the notice was issued.
The penalty will be termed as ‘Charge’ in cases full tax amount is voluntary paid with interest and penalty, within the specified time limit.
A reduced penalty of 5 per cent will apply where tax and interest are discharged within 30 days (under section 73) or 60 days (under Section 74A) of the adjudication order.
The minimum penalty of Rs 10,000 is recommended to be removed, in non-fraud cases. The maximum general penalty would be reduced from Rs 25,000 to Rs 10,000. In cases where the order only involves penalty and no demand of tax, an upper limit of Rs 40 crore would be provided on account of pre-deposit for appeals before the Appellate Authority or Appellate Tribunal.
These recommendations build on GST’s success and mark another step in its continued improvement. Together, these measures would further promote ease of doing business and contribute to a more efficient and taxpayer-friendly GST framework, said the factsheet.


